Money & Shopping
Korean Bank Account on a Tourist Visa? 2026 Guide
The payoff Assuming a passport is enough, or that it is impossible → knowing what official sources actually say, which documents to bring, and what to use instead if you are only visiting.
Research context: Search interest in opening a Korean bank account as a short-stay visitor, 2026
This is general information, not legal or financial advice. Bank rules differ by bank and branch and can change. Confirm with your chosen bank before visiting. No affiliate links.
The short answer
There is no single rule that says “tourists cannot open an account”, and there is no guarantee that a branch will accept you either. What the official sources do say:
- Before you have an Alien Registration Card (ARC), Invest KOREA’s guide lists a passport (or home-country ID) plus a document proving Korean residence. Examples it gives: a certificate of employment stating your place of residence, a utility bill receipt, a business registration certificate, a hotel voucher, or a hospital reservation document. It adds that if you choose a hotel voucher, you should check with the branch whether a hotel address can be used.
- You also need a document proving why you need the account (for example salary, part-time wages or business funds). If some documents are missing, the bank opens a restricted account with low daily limits.
- Shinhan Bank’s page says a passport alone cannot be used to open an account remotely through its app, and that short-term visitors without a Korean-issued ID must visit a branch in person with their passport and the required documents.
- The guide itself says the documents can differ by bank and branch, so check with the branch.
None of the official pages cited here state a rule specifically for B-1, B-2 or visa-free tourists, so whether a particular branch will take a short-stay visitor is something only that branch can tell you. If you are just visiting, a travel card is the lower-effort route (see below).
Decision table
| Your situation | Realistic option | What to do |
|---|---|---|
| Visiting for a short trip | Travel card, foreign card, cash | Skip the bank. See the travel cards comparison |
| Just arrived to work or study, no ARC yet | Account with passport plus residence proof, possibly restricted | Bring a residence document and a purpose document; ask the branch about hotel addresses |
| Have an ARC | Standard account opening | Bring passport, ARC and purpose documents (see E-2 visa checklist) |
| Remote worker on a long visa | Same as above once registered | See the digital nomad visa guide |
Steps for newcomers
1. Choose a bank with foreigner support
Invest KOREA’s guide lists foreigner-only call centers: Hana Bank 1599-6111, Shinhan Bank 1577-8380 (from overseas +82-02-3449-8380), and Woori Bank 1599-2288. Shinhan lists its Foreign Customer Call Center hours as weekdays 9:00 a.m. to 6:00 p.m. Woori’s page lists 1599-2288 with English as menu option 1.
2. Gather the documents
- Identification: passport (and ARC if you have it). Before the ARC, a home-country ID is also listed.
- Residence proof if you have no ARC yet: one of the documents listed above.
- Purpose of the account: the guide gives examples such as a certificate of employment, wage withholding receipt, employment contract, or for part-time wages a copy of the employer’s business registration and the contract.
- Tax-treaty reporting: if you are a foreign resident for tax purposes, the guide says an overseas taxpayer number, overseas address and overseas contact information are required, with a residence certificate from your home government as proof.
3. Expect a restricted account if documents are missing
The guide says that if some documents are omitted, a restricted bank account is opened. Under the Financial Services Commission’s announcement, from 2 May 2024 the daily limits for restricted accounts are ₩1,000,000 for ATM withdrawals, ₩1,000,000 for ATM transfers, ₩1,000,000 for internet and mobile banking, and ₩3,000,000 at the counter. Before that they were ₩300,000 (ATM and e-banking) and ₩1,000,000 (counter). The FSC page notes internet-only banks keep different limits, and that a few banks raised theirs a little later, so check your own bank.
4. Lift the limit later
Both the Invest KOREA guide and the FSC page say the limit can be lifted by proving your transaction purpose after opening. The FSC’s examples include proof of salary receipt such as a health insurance eligibility certificate or a withholding receipt, and it notes banks may ask for more documents.
Why the paperwork looks strict
The Invest KOREA guide gives two reasons. First, know-your-customer checks are mandatory under the Act on Reporting and Using Specified Financial Transaction Information, and a passport does not show your address, which is why Korean residence proof is added. Second, under the Special Act on the Preservation of Loss Caused by Telecommunications-Based Financial Fraud and Refund for Loss, you must submit a document proving why you need the account.
If you are only visiting
You can handle most trip spending without an account. This is what the providers’ own pages say:
- WOWPASS: cards can be reserved online or issued at self-service machines in places such as hotels and stations. Cash withdrawal is capped at ₩100,000 per withdrawal with a ₩1,000 fee. Its site says top-ups support 16 currencies and that the card works as a Tmoney card. Fees and card validity are shown on the machine and in the app, so check them there. More in our Tmoney card guide.
- NAMANE: its service manual lists up to ₩500,000 in Pay balance and ₩500,000 in Transit balance (₩1,000,000 per card in total), with a ₩500,000 cap per purchase.
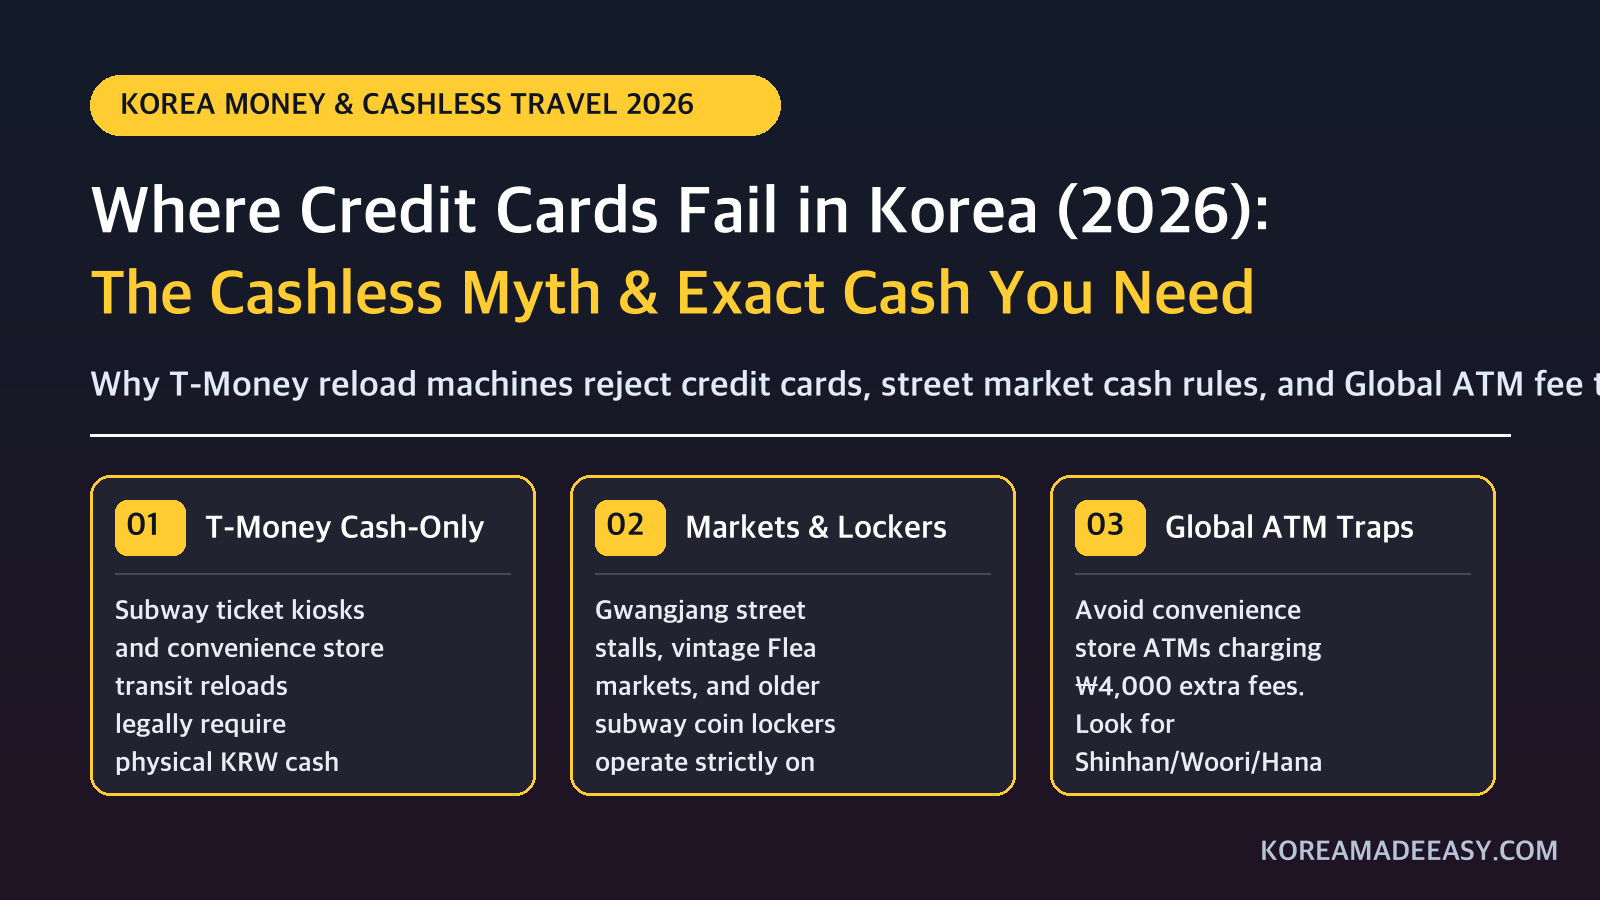
- Foreign cards and cash: if a kiosk rejects your card, see the kiosk fix and where cards fail and cash is needed.
Bringing cash: Korea Customs says arriving travelers carrying more than US$10,000 (or equivalent) in foreign currency, won notes or checks must declare it, and that failing to report can bring up to 1 year in prison, a fine of up to ₩100 million, or both.
Deposit protection: the FSC says maximum deposit protection coverage rose from ₩50 million to ₩100 million on 1 September 2025, covering banks, savings banks, insurers and investment firms. Some older bank pages still show ₩50 million, so use the FSC figure.
Who this is NOT for
- Short-trip visitors who only need to pay and ride transit. A prepaid card or your home card is simpler.
- Anyone who wants to open an account on behalf of someone else. The process above is for your own identity and your own documents.
- People who need a fully unrestricted account on day one. Official sources describe limits when purpose documents are missing.
Common mistakes
- Showing up with only a passport and no residence or purpose proof. The official guide lists both.
- Assuming a hotel voucher is automatically accepted. The guide tells you to ask the branch.
- Not checking branch hours. Woori’s foreign-student guide lists “Operating hours 09:00~16:00 (Weekdays)” in its banking guide, so do not plan an afternoon visit without confirming.
- Planning large transfers on a restricted account. The caps are ₩1,000,000 per day for ATM and e-banking.
- Carrying undeclared cash above the US$10,000 line when you enter Korea.
FAQ
Can I open a Korean bank account with just a passport? Invest KOREA’s guide lists a passport plus a document proving Korean residence and a document proving your account purpose. A passport alone is not what it describes. Shinhan says a passport alone cannot complete remote opening.
Can I open an account before my ARC arrives? The guide has a section for this case, listing passport or home ID plus residence proof. Whether a specific branch accepts a hotel voucher or other proof is for the branch to decide, so call first.
Why does my new account have a ₩1,000,000 daily limit? That matches the FSC limits for restricted accounts opened without full purpose documents. Submit purpose proof, such as salary-related documents, to ask the bank to lift it.
Can I open an account online from abroad? Shinhan’s page says remote opening through its SOL Global app needs a Korean-issued ID (Foreigner Registration Card, Domestic Residence Card or Permanent Resident Card) and a phone registered in your name. Ask other banks about their own rules.
Once an account is open, our guide to paying utility bills in Korea explains how electricity, gas, water and maintenance bills are usually paid.
Official sources to check
- Invest KOREA, foreigner bank account guide (PDF, August 2024): investkorea.org
- Invest KOREA, banking overview: investkorea.org
- Shinhan Bank, SOL Global account opening for foreigners: shinhan.com
- Financial Services Commission, restricted account limits: fsc.go.kr
- Financial Services Commission, deposit protection to ₩100 million: fsc.go.kr
- Woori Bank, banking guide for foreign customers: wooribank.com
- Korea Customs Service, currency declaration: customs.go.kr
- WOWPASS: wowpass.io
- NAMANE Card service manual: namanecard.com
- Always confirm with your bank before you go.
Sources
- https://www.investkorea.org/file/ik-en/How%20Foreigners%20Can%20Open%20a%20Bank%20Account%20in%20Korea.pdf
- https://www.investkorea.org/ik-en/cntnts/i-5056/web.do
- https://solgit.shinhan.com/sc26090283.html
- https://www.fsc.go.kr/po010101/82205
- https://fsc.go.kr/eng/pr010101/84977
- https://spib.wooribank.com/pib/Dream?withyou=ENENG0688
- https://www.customs.go.kr/english/cm/cntnts/cntntsView.do?mi=10800&cntntsId=5500
- https://www.wowpass.io/
- https://namanecard.com/en/service-manual/service-manual-301
This is independent guidance, not an official operator or government publication. Evidence and check dates vary by article. See our editorial and corrections policy for the distinction between source checks, personal visits and planning advice.